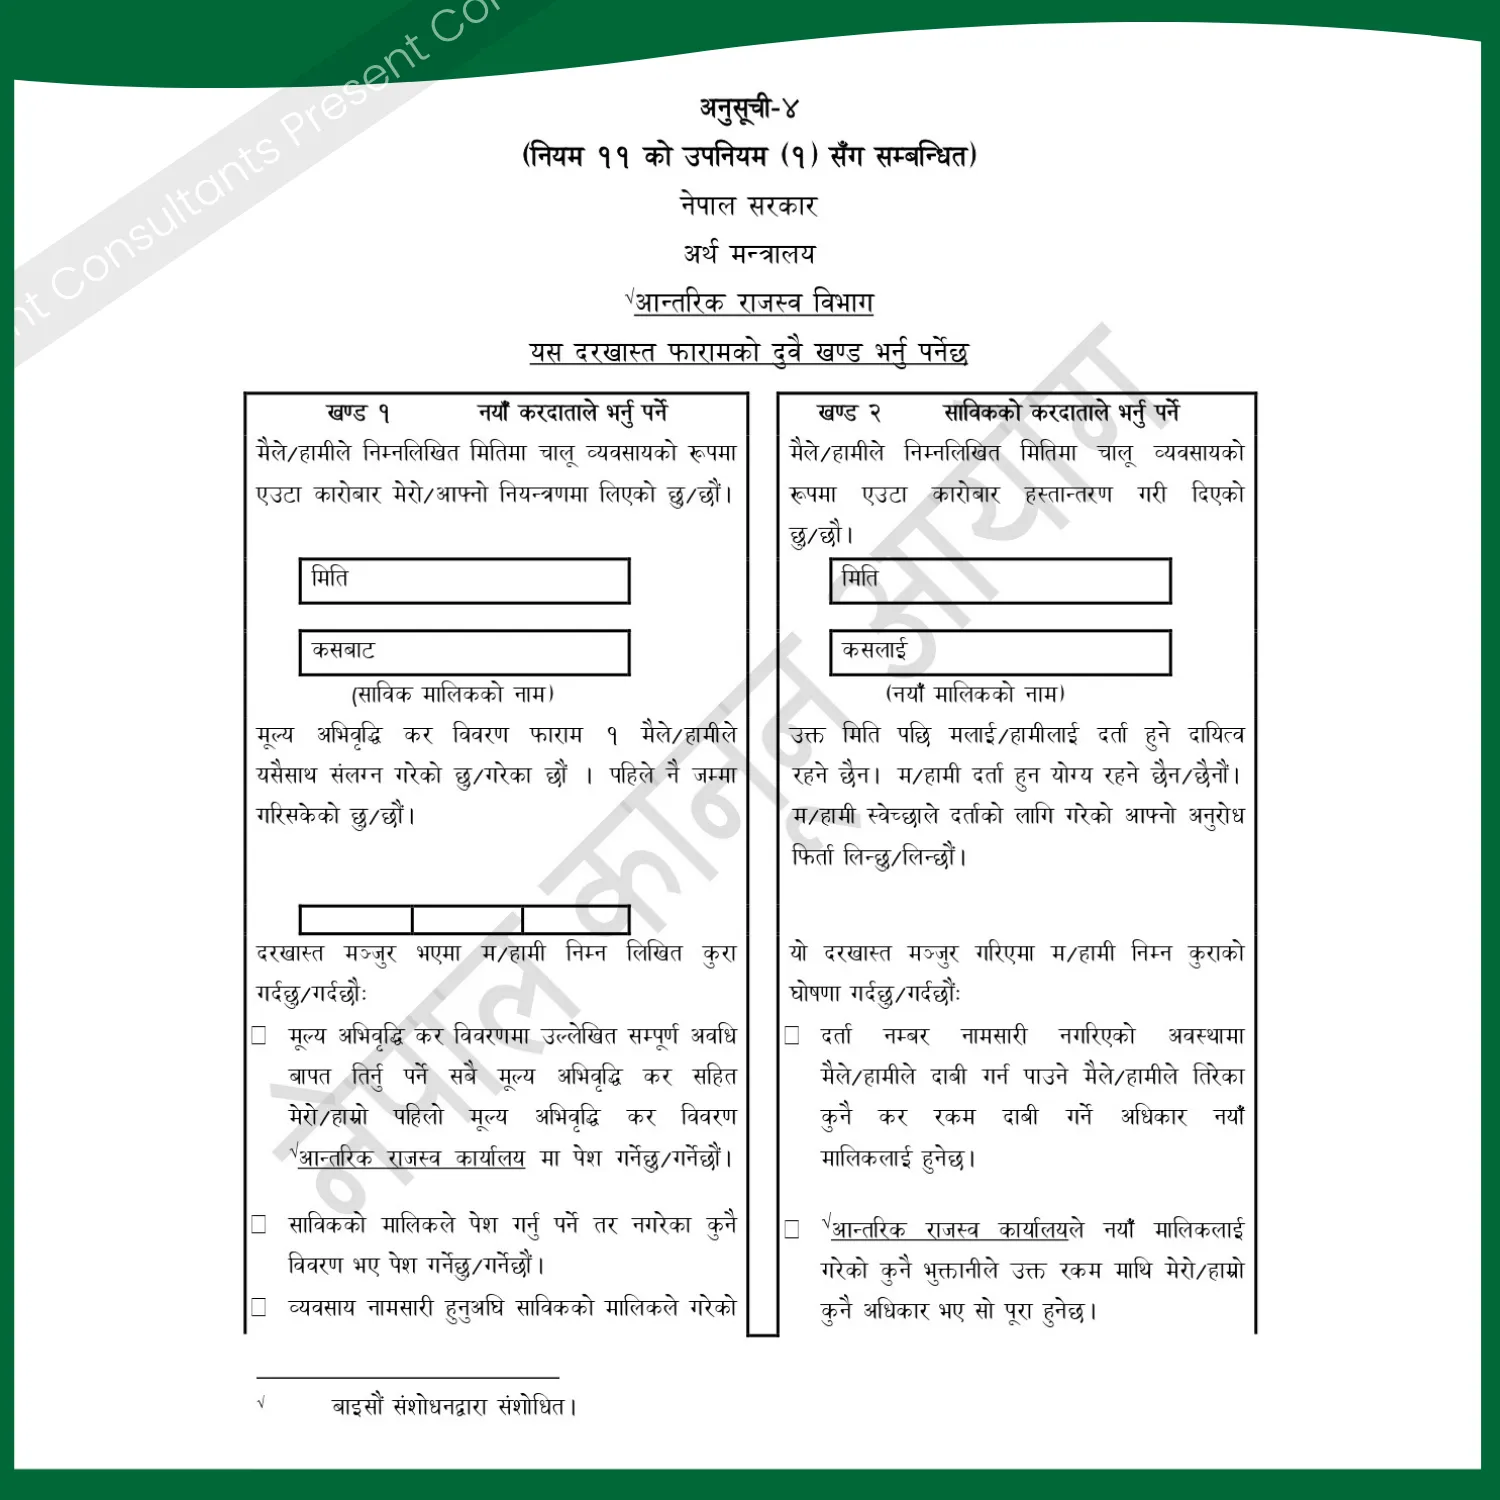
Under Section 5 and Section 26 of the Value Added Tax Act, 2052, when a registered taxpayer sells or transfers business ownership, the transferor must fully reconcile and settle all accrued tax liabilities up to the exact date of transfer. By law, the transferee who acquires the business ownership simultaneously inherits joint liability for any unpaid statutory taxes. Rule 11 of the Rules requires body conducting sale of business to inform the IRD. Furthermore, Rule 32 of the Value Added Tax Rules, 2053 mandates that a formal application for the cancellation or modification of VAT registration must be submitted to the concerned Tax Officer within 15 days of such business alteration.
Failure to notify the Tax Officer of the business transfer within the mandatory 15-day window triggers swift administrative fines under Section 29 of the Act. Additionally, if tax returns are delayed during the transaction, a daily penalty of 0.05% of the tax payable is levied, alongside an ongoing interest charge of 15% per annum under Section 19. Attempting to conceal asset transfers or evading VAT liabilities during the sale constitutes a serious tax offense, resulting in the full recovery of the evaded tax amount plus an immediate penalty of up to 100% of the tax amount, or potential imprisonment.